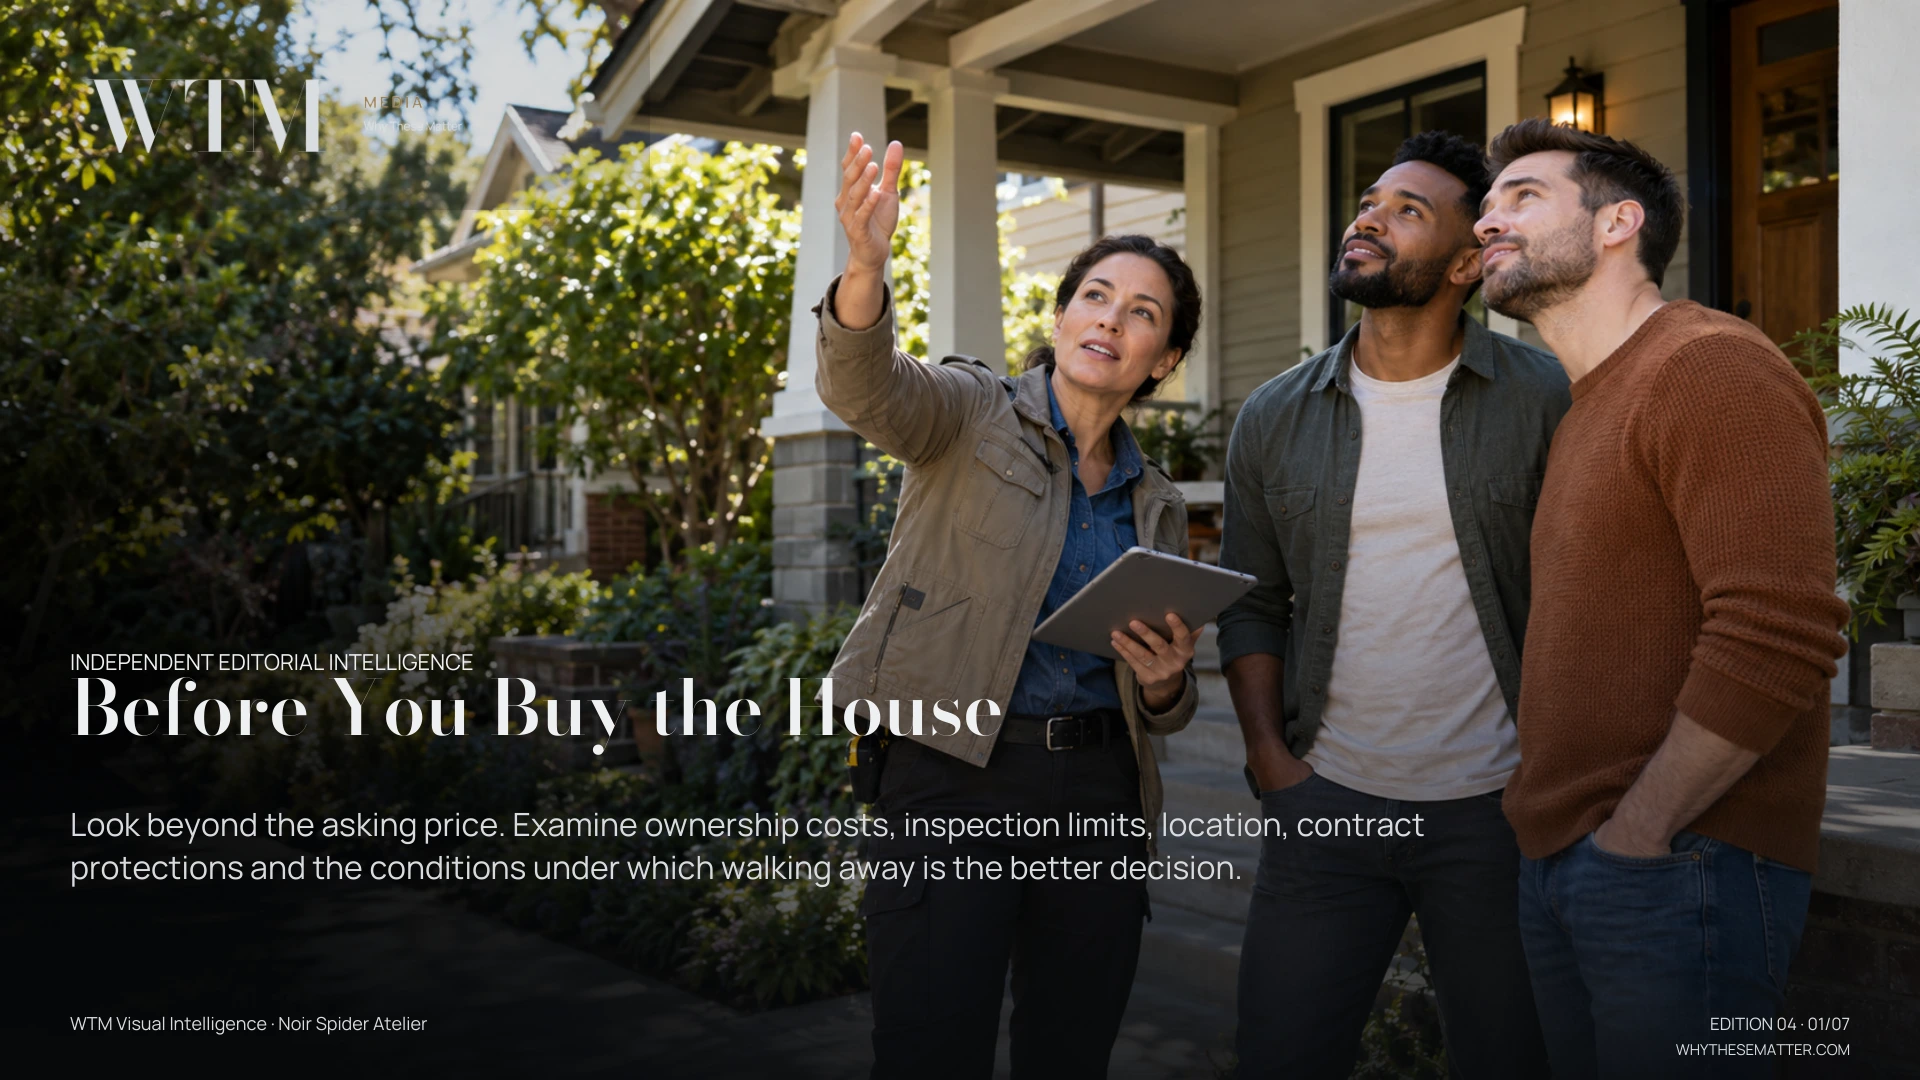
Look beyond the asking price. Examine ownership costs, inspection limits, location, contract protections and the conditions under which walking away is the better decision.
Buying a house is not merely choosing a place to live. It is acquiring a building, a location, a set of obligations and exposure to future costs. The asking price is only the opening number. The decision deserves the same diligence as any major long-term commitment.
Reader value: Look beyond the asking price. Examine ownership costs, inspection limits, location, contract protections and the conditions under which walking away is the better decision.
Start with principal and interest, then add property tax, insurance, utilities, association fees, maintenance, commuting and expected replacements. A mortgage payment of $2,100 can become a much larger monthly commitment once the other costs are included. Use actual local quotations rather than generic estimates. Prepare three budgets: normal conditions, a plausible insurance or repair shock, and a temporary reduction in household income. Set a maximum all-in housing commitment that leaves adequate liquidity.
The CFPB's Loan Estimate separates important loan and closing figures; it also warns that costs such as taxes and insurance may sit beyond principal and interest. [1] Obtain property-specific estimates and identify which charges are paid separately. Do not count an escrow estimate as proof that every future ownership cost is fixed.
Create a post-closing budget as well as a cash-to-close calculation. In an explicitly hypothetical example, $2,100 principal and interest plus $700 of other recurring ownership provisions equals $2,800, before any omitted costs. That arithmetic is a prompt to obtain real quotations, not a national cost estimate. Ask whether the household would still have accessible reserves once the purchase is complete.
Separate a lender's approval from the household's own judgement. Approval addresses the lender's criteria under the application; it does not establish that the remaining budget will support the life the buyer wants. Test care responsibilities, transport and irregular commitments alongside housing rather than treating every pound or dollar left after the mortgage as discretionary.
A useful comparison includes the cost of retaining options. Using almost all available cash to complete may leave little room for an early repair, a job change or a different care arrangement. Ask what remains accessible afterwards. The appropriate reserve is personal, but the question should be answered before the transaction creates an obligation that is difficult to reverse.
Review the assumptions with actual quotations as the purchase progresses. Insurance, association information or a repair estimate may change the original calculation. Update the decision sheet rather than preserving a maximum offer simply because it was agreed earlier. A more complete number can justify changing the plan even when the property remains attractive.
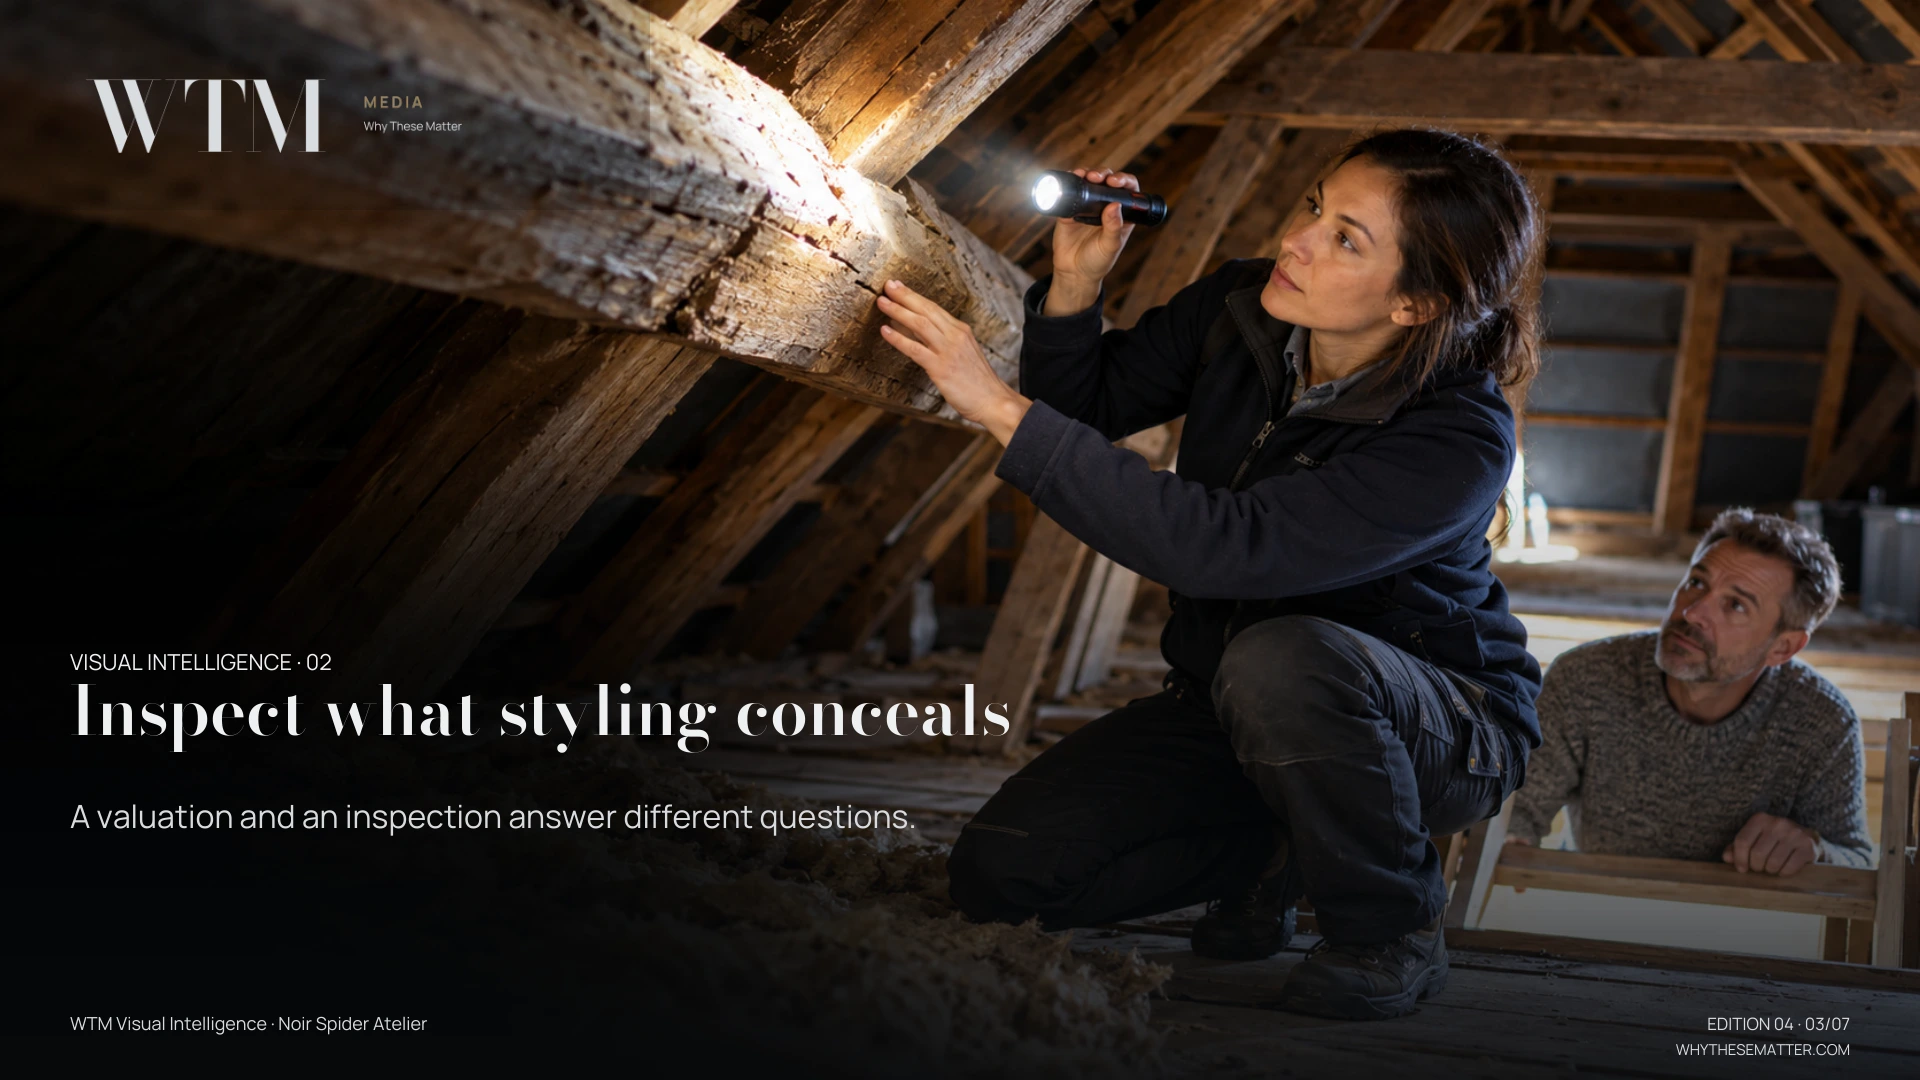
Fresh paint, appealing furniture and attractive photographs reveal little about roof condition, moisture, drainage, foundations or electrical safety. An independent inspection can identify visible concerns but cannot guarantee the absence of concealed defects. Older or unusual properties may require specialist assessments. Review inspection scope and exclusions before hiring. Request permit and repair records, assess heating and cooling equipment and seek specialist advice when structural, environmental or safety concerns arise. Do not confuse a seller's disclosure with an independent inspection.
An appraisal used by a lender concerns value; an independent home inspection concerns condition within its stated scope. The CFPB advises buyers to arrange an inspection and understand contractual implications. [2] Neither should be treated as an assurance that nothing will fail. Ask about access restrictions, excluded systems and circumstances requiring a specialist.
Turn findings into decisions rather than merely collecting a report. Which issue needs further investigation before a contractual deadline? Which requires a repair quotation? Which would make the property unsuitable regardless of a price adjustment? Keep cosmetic preferences separate from safety and material condition. Request clarification when a conclusion is uncertain instead of allowing an attractive photograph to settle the question.
Ask the inspector to distinguish observation, inference and recommendation. A visible sign may suggest a concern without establishing its cause or full cost. The buyer needs to know what was seen, what could not be inspected and what further expertise is warranted. That distinction helps prevent both misplaced reassurance and an exaggerated reading of an uncertain finding.
Obtain an appropriately scoped quotation where a repair matters to affordability. A general estimate from an interested party is different from a professional assessment of the actual work. Include access, disruption and any further investigation needed. Do not convert a report's list of observations into a reliable total repair budget without checking those assumptions.
Keep a dated record of unresolved issues and the person responsible for the next answer. The purpose is to make a decision before relevant deadlines, not merely accumulate documents. If important evidence cannot arrive in time, discuss the available contractual options with the appropriate professional rather than assuming that uncertainty can safely be carried through closing.
A property is tied to infrastructure, insurance markets, planning rules and environmental hazards. Review official flood information, zoning, access, local development proposals, commuting realities and service availability. Flood-map designations and insurer decisions are not interchangeable measures of risk. Visit the area at different times where possible. Obtain insurance quotations before contractual deadlines, review association rules and ask whether expected future uses of the home are permitted.
Use official flood information as one input, then ask the insurer how it assesses the specific property. FEMA explains flood mapping as part of understanding flood hazards; a map is not a guarantee against a future loss. [3] Obtain the relevant coverage terms rather than assuming all water damage is covered.
Consider ordinary use as well as future exposure: the actual commute, access to care, noise at night and any restriction relevant to intended work or alterations. Confirm planning and association information with the appropriate authority. These are due-diligence questions, not predictions that a neighbourhood will rise or fall in value. Test whether the location works without depending on a proposed improvement that has not been delivered.
Examine the difference between a place that works for a visit and one that works for ordinary life. Try the route to work, consider access when weather is poor and ask how a household member without a car would manage. These are practical use tests; they do not require predicting a neighbourhood's future market reputation.
Check which appealing features depend on someone else's future delivery. A proposed station, redevelopment or service improvement may be important to the sales story but remain uncertain. Ask what is formally approved, funded or operating. Decide whether the property still meets the household's needs if a proposed improvement is delayed or does not occur.
Treat insurance availability and terms as part of the property decision. Ask about relevant exclusions, deductibles and conditions, and obtain advice where the wording is unclear. A map, a seller's experience and an insurer's quotation answer different questions. None should silently substitute for understanding the risks the buyer would retain.
Financing, inspection and appraisal contingencies, deposits, closing deadlines, title conditions and association assessments can materially change the buyer's exposure. The legal position varies by jurisdiction, so general internet checklists cannot substitute for competent local advice. Read the full agreement and its deadlines with the relevant professionals. Confirm what fixtures and equipment convey, how disputes are handled and what happens if financing or inspections fail. Avoid waiving protections without understanding the potential loss.
Create a contract calendar with the relevant professional: deposit date, inspection deadline, finance deadline and closing conditions. For each, ask what action preserves a protection and what happens if it is missed. A familiar term can have different legal effects across jurisdictions and contracts; WTM is not asserting a universal right to cancel.
Verify changes in writing and ask who is responsible for unresolved title, permit or association issues. Avoid relying on an informal assurance that a serious issue can be fixed later. This is especially important when several professionals are involved: a lender's willingness to lend is not a substitute for the buyer understanding the contract and the risks personally retained.
Translate an important clause into a consequence the buyer can explain. What money is exposed, what condition must be met and who must act by which date? If that explanation remains uncertain, ask for professional clarification. Familiarity with a term from another transaction is not evidence that the present agreement gives the same protection.
Keep the communication chain clear when several professionals are involved. An agent, lender, inspector and legal adviser have different roles. Record who is answering which question and whether their advice addresses the buyer's particular concern. A reassuring response outside someone's scope should not close an issue that requires another person's expertise.
Review a material change as a new decision. A revised completion date, financing term or seller undertaking can alter the original allocation of risk. Read the final written version and ask how it affects existing protections. The discipline is to understand the agreement being signed, rather than rely on the transaction as it was first described.
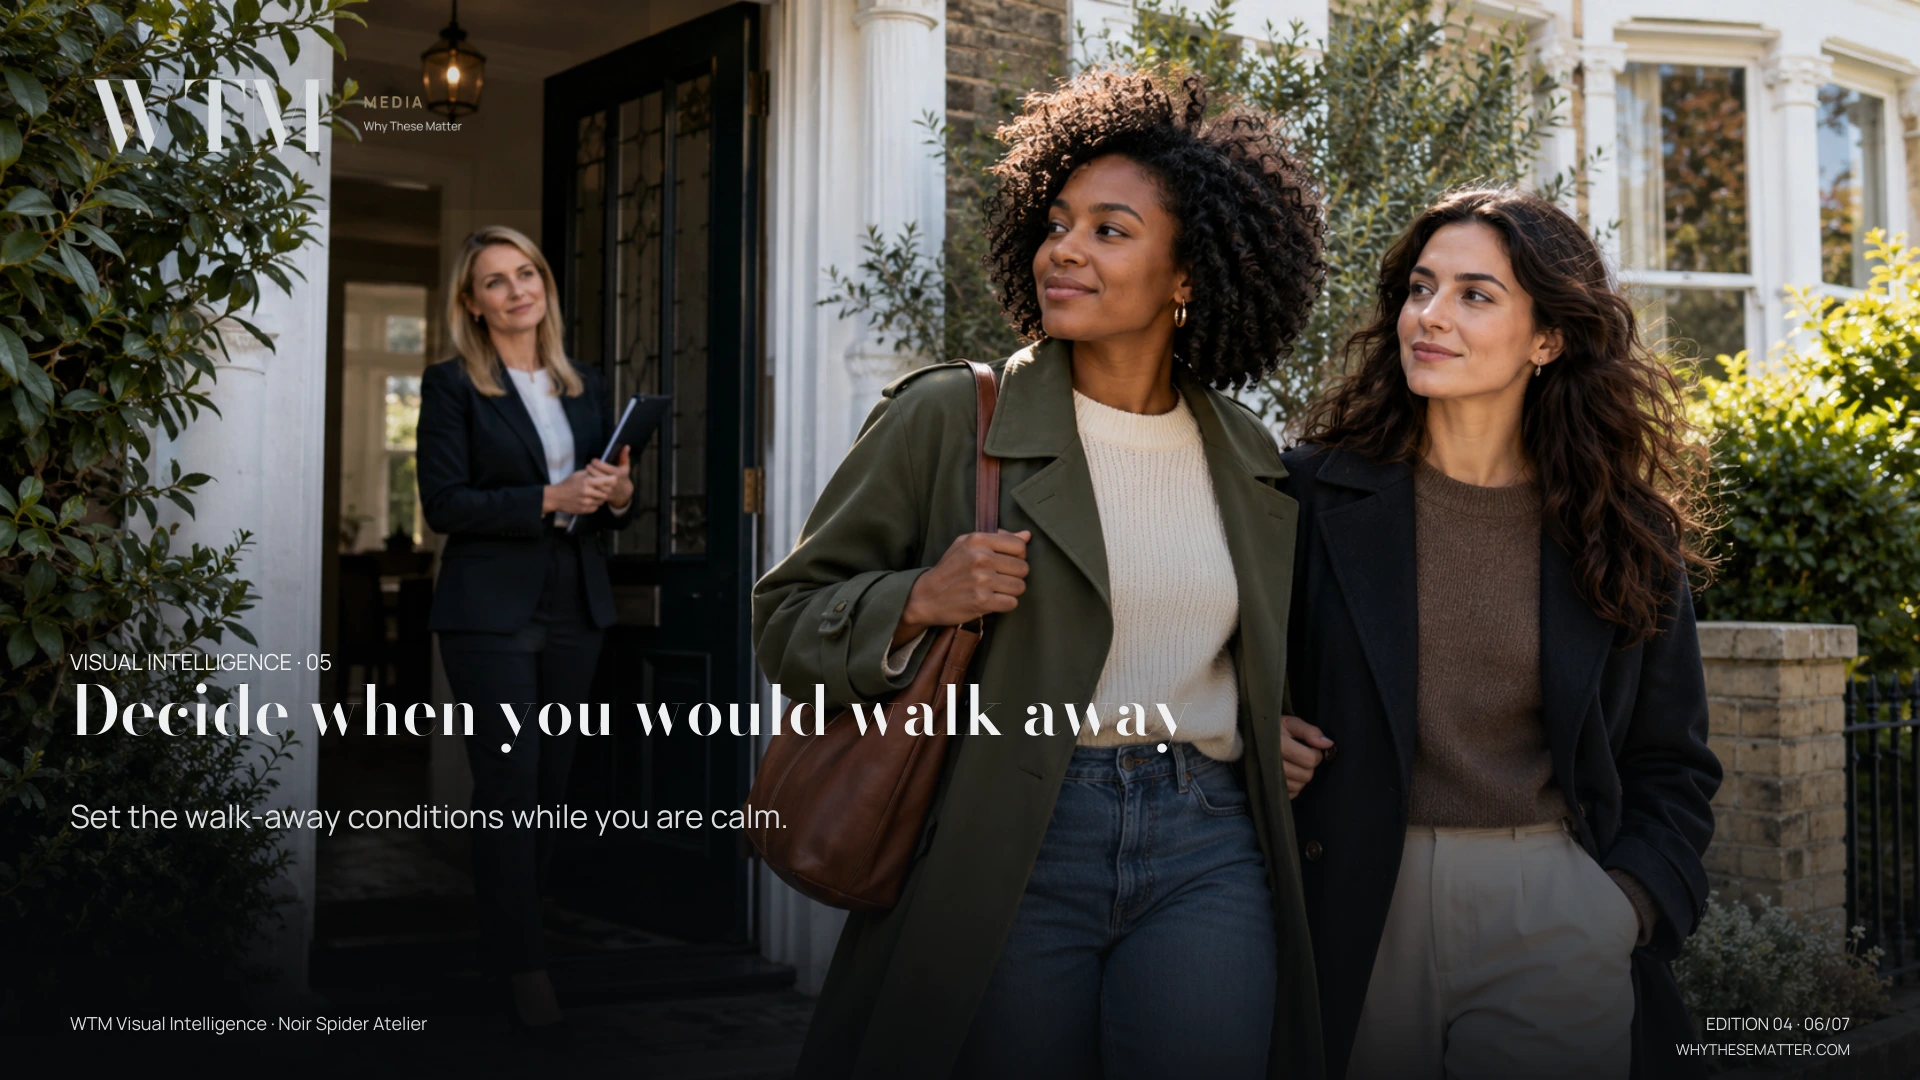
Emotion and competitive bidding can push a buyer beyond the original budget. Before making an offer, write down maximum total ownership cost, minimum post-closing reserves and non-negotiable safety or title conditions. Include transaction costs if a move becomes necessary sooner than expected. Use a decision sheet with three columns: evidence confirmed, unresolved questions and deal breakers. A house should fit a plausible future, not depend on perfect income, perfect repairs and guaranteed appreciation.
Write down a maximum total commitment and a minimum acceptable post-closing position before bidding. Also record the evidence required to remove uncertainty. An unresolved concern does not become harmless because other buyers are interested; nor does every inspection item justify abandoning an otherwise suitable property.
Use a second reader who has no incentive to close the transaction, if available. Ask them to challenge the assumptions rather than merely approve the choice. Include the possibility of needing to move sooner than planned. A disciplined decision can still be emotional and hopeful; it simply does not require uninterrupted earnings, effortless repairs or guaranteed appreciation to remain viable.
A walk-away condition is more useful when it is specific. 'Too expensive' can shift under pressure; a maximum all-in commitment and a minimum acceptable reserve are easier to compare with new evidence. Include conditions that cannot be solved with a discount, such as an unsuitable daily journey or a material uncertainty the buyer is unwilling to retain.
Separate disappointment from a failed decision. Time spent investigating a property can produce the valuable conclusion that it is unsuitable. Treating that effort as something that must be recovered by completing the purchase can distort the next choice. The relevant comparison concerns future obligations, not whether the search already consumed several weekends.
Keep a concise account of why the chosen home meets the agreed conditions. It should identify confirmed evidence and the risks deliberately accepted. This is useful after purchase too: it provides a starting point for maintenance, budgeting and future reviews. A considered commitment acknowledges uncertainty while making clear why this particular uncertainty is manageable.
A house purchase can support security and belonging while also reducing flexibility. Both effects belong in the decision. The task is to understand the obligations being accepted, the evidence supporting them and the circumstances in which the household could still adapt if work, health or care needs changed.
The asking price does not describe the whole commitment. Monthly operation, repair needs, local conditions and contractual risk together shape ownership. A buyer should be able to explain those elements in plain language, with appropriate professional help where needed, before an urgent timetable replaces the original reasoning.
Return on Investment concerns the service the home provides relative to the full resources it requires. Return on Integrity concerns honest information, understood responsibilities and a process that does not disguise material uncertainty. A purchase can be appealing while still failing either test for a particular household.
Use disagreement constructively before the commitment becomes hard to reverse. A second reader may notice an omitted assumption or a question whose answer was inferred rather than obtained. Their role is not to approve every preference. It is to help distinguish a deliberate acceptance of risk from a gap in understanding.
Keep permission to pause or leave when evidence fails the agreed conditions. That can be disappointing without being a failure of the search. The purpose of diligence is to preserve the future life the property is meant to serve, rather than make completion itself the only measure of a successful process.
A sound homebuying decision preserves the life the home is meant to support. The strongest offer is not necessarily the highest one; it is an informed commitment whose obligations the buyer understands. Gather evidence before urgency takes over, and keep the permission to walk away.
Evidence reviewed 18 October 2026; primary-source release check completed 28 October 2026. This is public-source educational editorial analysis. Numerical scenarios and WTM exercises are illustrations, not measured outcomes or personalised professional advice. Recheck changing guidance before making a decision.
Visual provenance: Illustrative scenes with fictional adults. These visuals support the analysis; they do not document reported events, identify actual research participants or imply endorsement. WTM Visual Intelligence · Noir Spider Atelier.
Download the WTM Visual Intelligence PDF · Support independent WTM journalism
Why These Matter - WTM MEDIA is an independent editorial platform exploring the forces shaping our world—through people, culture, commerce, design, systems, and governance. Connecting the dots between today’s headlines and tomorrow’s realities.
article-support-3
Noir Spider Atelier
article-support-2
Noir Spider Atelier
article-support-1
Noir Spider Atelier

press-partnership
Noir Spider Atelier
press-reader-desk
Noir Spider Atelier
resource-access
Noir Spider Atelier
membership-example
Noir Spider Atelier
membership-tools
Noir Spider Atelier
membership-reader
Noir Spider Atelier
membership-public
Noir Spider Atelier
pathway-design
Noir Spider Atelier
pathway-institutions
Noir Spider Atelier
pathway-technology
Noir Spider Atelier