For the past two decades, business has lived under a spell — the belief that technology is the ultimate disruptor. We’ve worshipped at the altar of innovation, measuring success by how quickly we could automate, digitise, and optimise. Tech has indeed changed the way we live, work, and connect. But here’s the inconvenient truth: In the next decade, technology won’t be the competitive advantage. Trust will.
For the past two decades, business has lived under a spell — the belief that technology is the ultimate disruptor. We’ve worshipped at the altar of innovation, measuring success by how quickly we could automate, digitize, and optimize. Tech has indeed changed the way we live, work, and connect.
Let’s be honest — there’s a limit to how much faster, smaller, or smarter our tools can get before they blend into the background. The world’s most valuable companies already operate with AI, predictive analytics, and hyper-efficient supply chains. Incremental improvements will still happen, but the market is saturated with “smart” everything.
The real differentiator won’t be whether your product has the latest algorithm — it will be whether people believe in you enough to let your algorithm into their lives.
In an age where consumers know their data is being harvested, where misinformation moves faster than truth, and where every scandal is a viral moment away, trust is no longer a soft virtue. It’s an economic asset.
Brands that win the next decade will do so because they are predictably ethical. Not perfect — but transparent, consistent, and willing to hold themselves accountable when they get it wrong.
This isn’t just about public image. A Deloitte study showed companies with high trust levels outperform their industry peers by up to 400% in market cap. Why? Because trust compresses the time it takes to make decisions, negotiate deals, and build loyalty. It accelerates business in ways no code or chip can.
Ironically, the same companies pouring billions into R&D often neglect to innovate in trust-building. They mistake compliance for credibility, thinking that following the rules is enough. But compliance is the floor; trust is the ceiling.
Employees don’t stay for ping-pong tables or hybrid schedules. They stay because they trust leadership. Investors don’t double down because of quarterly reports alone. They invest because they trust the vision. Customers don’t evangelize a brand because of its features — they do it because they trust what the brand stands for.
Here’s the kicker: trust cannot be coded, outsourced, or bought. It is built — slowly, vis ibly, and often painfully — through decisions that prioritize long-term relationships over short-term wins.
The companies that will dominate the next era are already making moves:
If You’re Not Building Trust, You’re Burning It
Trust isn’t neutral. You’re either adding to it or depleting it. Businesses that treat it as an afterthought will discover too late that no amount of tech can compensate for its absence.
The irony is that in a world obsessed with disruption, the most disruptive thing you can do is become deeply, visibly trustworthy. Because while technology may change the game, trust changes the player.
This isn’t a feel-good opinion piece. It’s a strategic forecast for leaders, investors, and decision-makers who are betting on where the next wave of market power will come from. The companies that grasp this shift early will:
In other words: trust will become the moat no competitor can breach — and the ones who build it now will own the decade ahead.
Most headlines describe Citigroup’s technology transformation as another expensive digital modernisation programme. That framing misses the larger story; the real transformation is institutional. Technology has become the visible expression of something much deeper: organisational redesign. Under CEO Jane Fraser, Citi is attempting one of the most complex reinventions in modern banking—not merely replacing ageing software, but rebuilding governance, simplifying decision-making, redesigning accountability, reducing organisational complexity, and restoring confidence after years of regulatory scrutiny.Tim Ryan’s arrival from PwC represents more than a technology appointment. It reflects a growing recognition that technology leaders increasingly function as institutional architects. Their responsibility is no longer confined to servers, software, or cybersecurity. They now redesign how information moves, how decisions are made, how risks are managed, and ultimately, how organisations earn trust. The future of banking will not be determined by whichever institution deploys the most artificial intelligence. It will belong to those capable of redesigning themselves whilst continuing to operate at global scale.

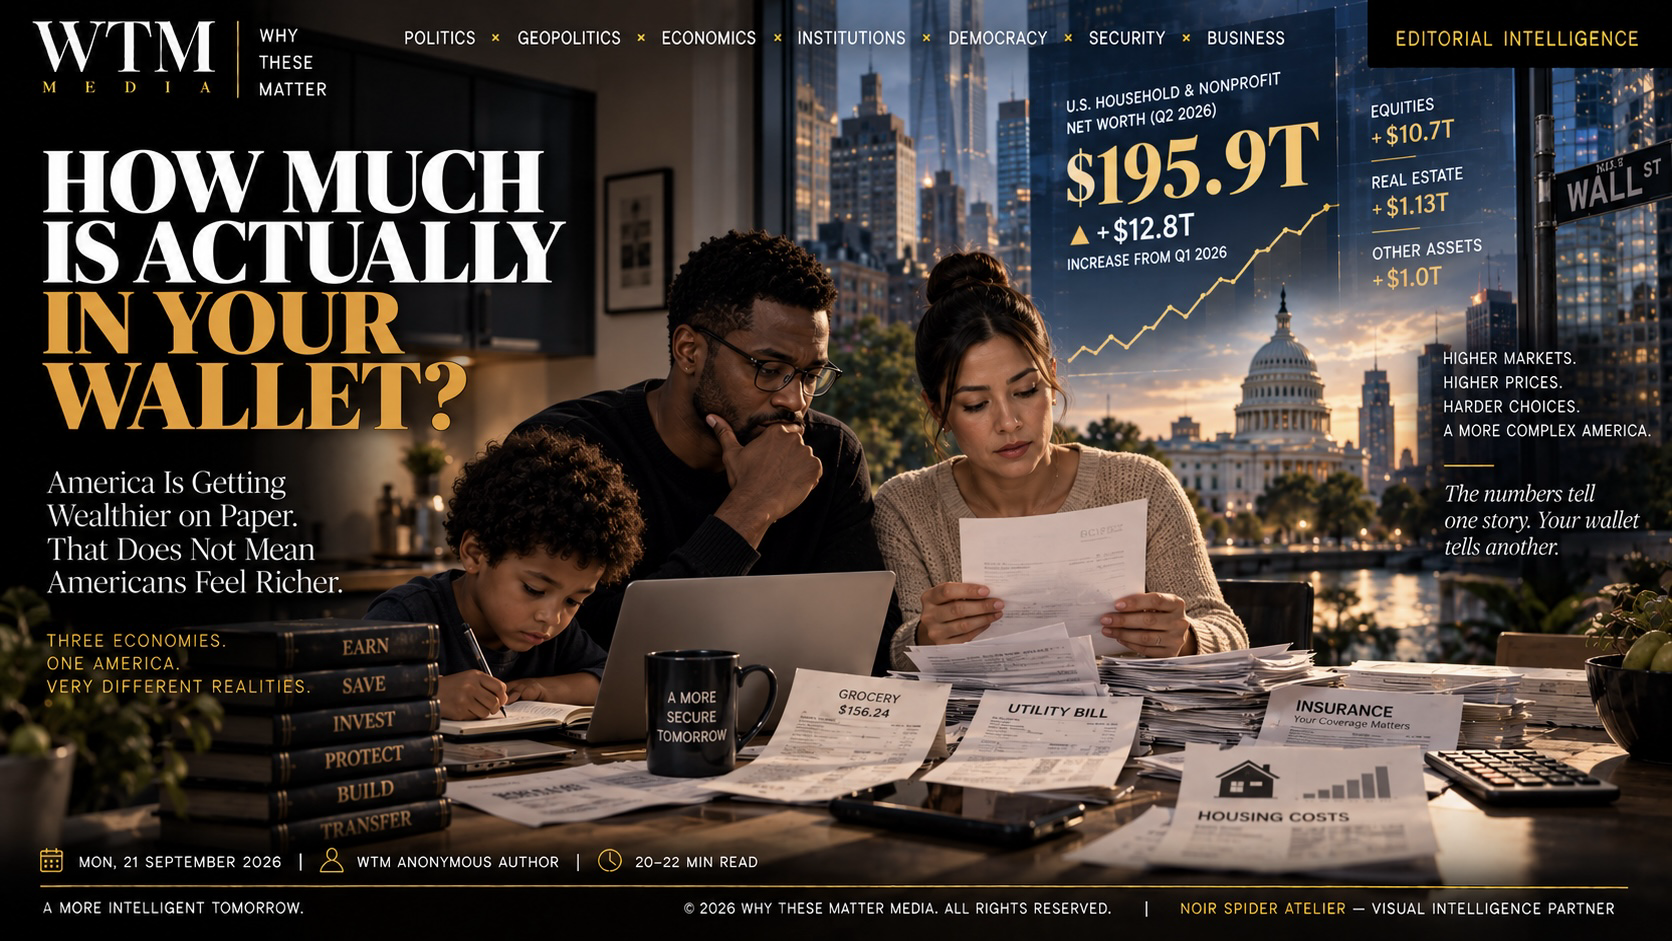
America became dramatically wealthier during the second quarter of 2026. The Federal Reserve calculates that household and nonprofit net worth increased by approximately $12.8 trillion in three months, reaching $195.9 trillion. Corporate equity holdings accounted for roughly $10.7 trillion of that quarterly increase. On paper, it was an extraordinary expansion of American wealth. But paper wealth and lived prosperity are not synonymous. Consumer prices in August were 3.4% higher than a year earlier, while real average hourly earnings for private-sector employees were 0.3% lower. A worker can therefore watch the country’s aggregate balance sheet expand while discovering that the same hour of labour buys slightly less. Neither statistic invalidates the other. They are measuring different economies. WTM proposes that Americans increasingly experience three overlapping economic systems: the Wage Economy, which determines what labour pays; the Cost Economy, which determines what life requires; and the Asset Economy, which determines what accumulated ownership does without another hour of labour being sold. The distribution matters. Federal Reserve data for the first quarter of 2026 show that the bottom half of households collectively held only about $590 billion in corporate equities and mutual-fund shares. The top 0.1% alone held approximately $13.33 trillion; the remainder of the top 1% held another $14.31 trillion. Rising markets can therefore increase national wealth enormously without distributing the increase evenly. This is not evidence of a conspiracy. It is evidence of architecture. The American wealth divide is not only about who earns more. It is increasingly about who owns the machinery that compounds while everyone else is working. The question for the household is consequently not merely: How much do I make? It is: What enters my wallet, what leaves it, what compounds against me — and what do I own that can compound for me?

On 3 November, Americans will elect all 435 members of the House of Representatives and decide 35 Senate contests: 33 regularly scheduled Class II elections and two special elections. Yet describing the event as 470 congressional races understates what is actually being allocated. Congress is not simply another arena for the country’s political arguments. It is part of the machinery through which those arguments become law, money, appointments, investigations, military authority and international commitments. Its constitutional powers include appropriations and war authorities; the Senate participates in treaties and confirmations; and congressional committees oversee executive operations. The numerical paradox is striking. Every House district will vote, yet Reuters identifies only about 50 of 435 House contests as meaningfully competitive and reports that Democrats require a net gain of three seats to take the chamber. In the Senate, Reuters identifies nine especially consequential contests, with Democrats needing four additional seats for control. These are not predictions. They reveal something structurally important: enormous national power can turn on comparatively small electorates. And the country holding this election is operating in a world that is not waiting for the result. War and instability are affecting energy markets. Treasury yields have approached 5%. Russia’s war against Ukraine continues. Gulf states are pursuing diplomatic calculations of their own. Trade partners are developing leverage against American policy. WTM therefore treats the 2026 midterms not principally as a referendum on a president, party or ideology, but as an institutional allocation event. The relevant question is larger than who wins. What governing capacity will America possess after the votes are counted — and what will the rest of the world conclude from the answer?